
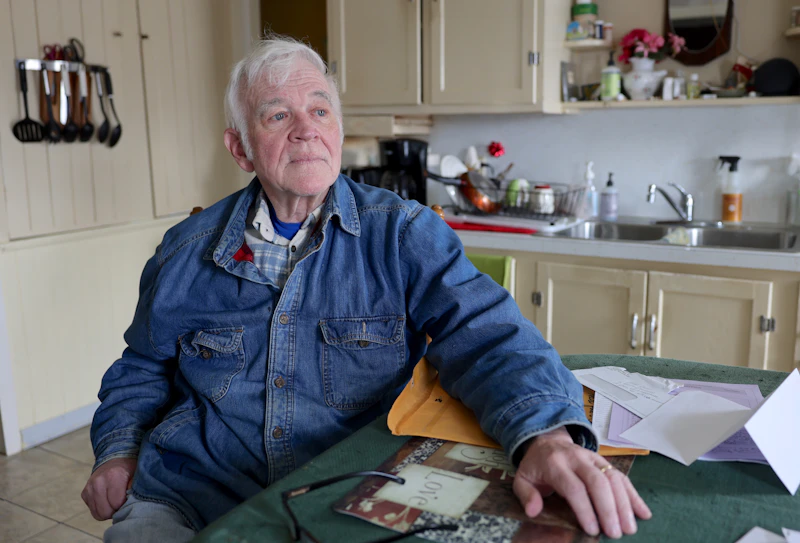
For over half a century, Miles “Burt” Marshall had a downtown office in sleepy Hamilton, New York within walking distance of Colgate University. Everyone in town knew the friendly fellow who rode his bike down Main St. on a daily basis. Burt handled everyone's insurance (parents, then their grown-up children, and even grandchildren), did their taxes, sat on local boards, owned rental properties, and paid for Little League uniforms for the kids.
Marshall was the kind of small-town businessman who calls his clients on their birthdays. His 15 employees, all women, got a fresh bouquet of flowers on their desk every Monday. Everyone trusted Burt. When the townspeople would visit his office, they’d see a sign on the wall guaranteeing them, at a time when banks were paying around one percent, a market-defying eight percent return (sometimes 10 percent) if they invested in his too-good-to-be-true “investment fund.” Only on that small sign did Marshall advertise this enticing opportunity, for reasons that would later become obvious.
Over the years, Marshall ensnared approximately 1000 Hamiltonians with his handshake-style deals. They’d fork over their money, and he'd hand them a handwritten, unsecured promissory note. But investment fund investors receive shares, not promissory notes. That was one of the first red flags that went unnoticed. Essentially, Marshall's customers were making uncollateralized loans to their trusted advisor—another red flag. Some invested their entire retirement savings with Marshall who, unlike banks and insurance companies, was subject to no legal minimum requirements of reserve holdings to protect such sizable investments—red flag number three, so far.
Marshall’s lenders would receive regular statements. Their compounding interest was printed on the page, but the numbers represented only what they were owed, not funds available for them to withdraw. It all looked kosher. When customers asked Marshall how he could afford to pay such a generous interest rate, he’d cite—verbally, not on paper—his ever-expanding rental empire of student housing.
Marshall took potential clients around town to show them his rental properties as an assurance that there were hard assets behind their investments. What the potential clients didn't know, however, was that the rental properties weren't generating sufficient funds to meet his obligations. And there was no way to look into it—red flag number four. The guy who’d hand out gift bags with maple syrup and honey with the printed message, “Stick with me. I'll sweeten your savings” ran a private business, so he was under no legal obligation to disclose the details of his finances.
When such a shortfall occurs, there are two choices: admit you can't meet your obligations or find another way to fund them. As the now-imprisoned crypto-felon and former billionaire, Sam Bankman-Fried also did, Marshall chose the latter. So he took the money his new investors gave him and, instead of investing it for them, used some of it to pay off earlier, older investors who wanted to begin withdrawing their funds. The rest he used to funnel millions into his other failing businesses and a lavish personal lifestyle.
Burt Marshall was running a Ponzi scheme along the lines of the one that put Bernie Madoff, the most famous Ponzi scammer, in prison for life. What Marshall referred to as the “Eight Percent Fund” was, in fact, a borrowing scheme disguised as an investment fund.
There were two reasons Marshall advertised his scheme only on a small sign in his office. All of his target market already came into his office every day, and they saw the sign. Moreover, had the SEC learned of his sketchy activities, regulators would've shut him down.
The first warning sign that Marshall’s three-decades con was about to collapse was when clients tried to cash in their investments and he'd tell them it could take a couple of weeks because the money was ostensibly tied up in his “lucrative” real estate holdings. When the clock ran out on that bluff, Marshall claimed that a brief but serious illness had set him back by about $600,000 because he’d been temporarily unable to work on tax returns. Though it would take completing approximately 2000 returns to generate that figure in a “brief period,” nobody notice. Marshall had sold his promissory notes on the strength of his real estate portfolio, not his promise of good health during tax season.
In March 2023, New York State Attorney General Letitia James publicly announced that her office was launching an official probe into Marshall's “Eight Percent Fund.” Promissory note holders mounted a massive "run on the bank," forcing Marshall to file for Chapter 11 bankruptcy protection less than a month later. His “investors” would eventually receive pennies on their dollars for the total of $50 million they’d paid into his fund. They got zero of the promised eight percent interest. Including that interest, the total loss to the townspeople was $94 million.
Burt Marshall fashioned himself along the lines of George Bailey in It's a Wonderful Life—a small-town businessman whose greatest asset is the trust people place in him. But for the people of Hamilton, he was more like a cross between con artist Tom Ripley in The Talented Mr. Ripley and Larry Vaughn, the mayor of Amity Island in Jaws. Burt Marshall was Hamilton's Great White shark—a shark smart enough to lurk too far from the shore to be noticed.
Marshall pleaded guilty to three felony charges on April 28, 2026. On June 11, 2026, Madison County Court Judge Rhonda Youngs handed down a prison term of four to 12 years to the 74-year-old fraudster.
Bernie Madoff stole approximately $64.8 billion from his investors, but Marshall is no less evil because his total theft (much of it perpetrated on the elderly) on a numbers basis pales in comparison. Well after Marshall's crimes had been exposed, he continued biking around Hamilton's streets as if nothing had happened.
There are many lessons to be learned from this story. One is that high-trust cultures, while offering many advantages, are susceptible to disguised predators on the inside who exploit that trust. Doctors, lawyers, and Colgate professors all fell prey to Marshall’s act because they’d become too complacent to see all the red flags popping up around him for years.
Trusting Marshall when it came to sponsoring Little League teams is fine. But when pondering critical, survival-related moves like investing all of one's retirement funds in one unregulated instrument, it's better to take the Ronald Reagan approach—“trust, but verify.”